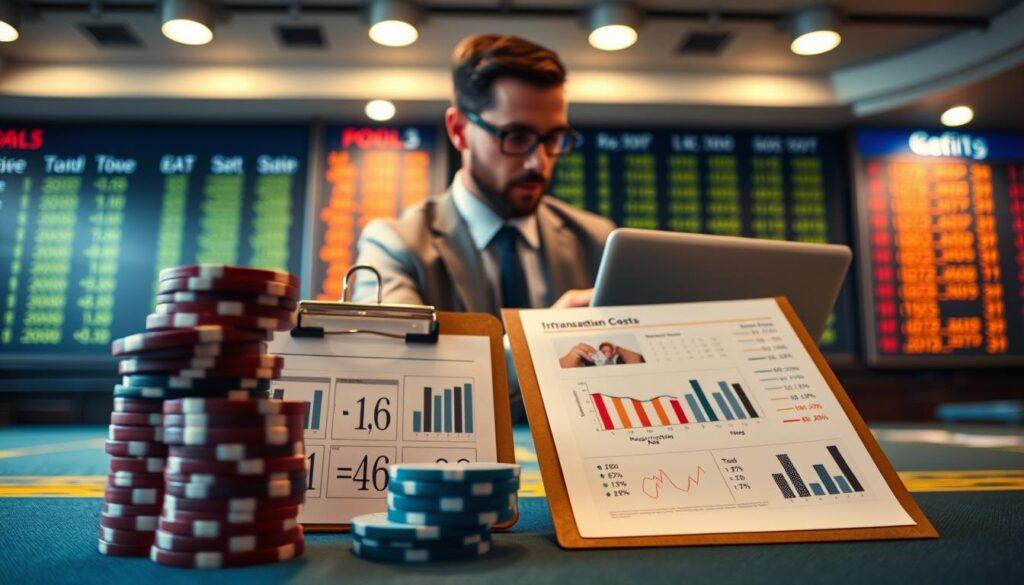
Many people start a betting backtest with too much confidence, like a tourist in Vegas. They ignore the hidden risks. Even sharp analysts can fall into the trap of thinking a backtest is perfect.
A backtest is like a lie detector for your strategy. It’s not about making a perfect chart. It’s about knowing if you’re really good or just lucky.
There are many common mistakes. Overfitting is like memorizing answers for a test. Look-ahead bias is like cheating by knowing the future. Survivorship bias is like only testing winners.
Think of betting like playing poker. Your strategy is like having pocket aces. But ignoring your opponent’s behavior can lead to big losses. Backtesting without understanding the situation is like playing blind.
Backtesting is where honesty starts. It helps separate real skill from random luck. Want to learn more? Check out backtesting betting strategies and how to handle the challenges.
Train Test Split Temporal Integrity and Walk Forward Design
Splitting data into a 70/30 ratio for betting backtests is not enough. It’s like trying to win a marathon in flip-flops. You might finish, but you won’t win any medals. Temporal integrity is key for robust analysis. It’s the foundation of your analytical skyscraper.
Betting markets have a memory, but it’s not reliable. It’s like the fragmented recollections of a soap opera character. What worked in the NFL regular season might not work in the playoffs. This is where walk forward analysis comes in.
Walk forward analysis is not just a buzzword. It’s a rigorous process. It involves training on a rolling window of data and testing on the next period. Then, you step forward and repeat. It’s like a series of mini-backtests asking if the edge persists over time.
Let’s break it down further. Randomized out-of-sample testing is the best. It randomly selects non-congruent dates for your holdout set. This ensures you’re not just testing on a bull market. Stability in P&L distributions across these walk-forward windows is your true green light. Forget the headline Sharpe ratio or the aesthetically pleasing equity curve. It’s all about stability. Everything else? Just expensive confetti.
| Method | Description | Advantages |
|---|---|---|
| Train-Test Split | Divides data into training and testing sets. | Simple and quick to implement. |
| Walk Forward Analysis | Uses rolling windows for training and testing. | Tests edge persistence over time. |
| Randomized Out-of-Sample Testing | Selects random dates for validation. | Avoids bias from market conditions. |
In conclusion, if you’re serious about your betting strategies, ditch the basic train-test split. Embrace walk forward analysis and randomized out-of-sample testing to truly understand your edge. For more insights on backtesting, check out this guide.
Include Frictions Limits Hold Percentages Rejection Rates and Juice Changes
Betting without thinking about transaction costs is like trying to find your way in a maze without seeing. It can make traders think they’re winning when they’re actually losing. Transaction costs in betting are more than just the vig or juice. They include many frictions that can change your results a lot.
Think about the drag of bet rejection rates when books limit sharp action. Hold percentages can change a lot by market and operator, affecting your profit. And don’t forget the small juice changes that can happen when a line moves against you before you can place your bet. I’ve seen strategies that looked great on paper but actually drained accounts once frictions were added.
To show how these factors can affect your betting, here’s a table:
| Factor | Impact on Profitability | Example Scenario |
|---|---|---|
| Transaction Costs | Reduces overall returns | Average edge of 2.3% with costs of 3.1% |
| Bet Rejection Rates | Limits possible profits | Sharp action often gets limited |
| Hold Percentages | Affects net returns | Varies by market and operator |
| Juice Changes | Impacts execution price | Line moves against you |
The math is tough but clear. If your edge per bet is 2.3% but the effective juice plus slippage is 3.1%, you’re losing money slowly. Position sizing is also key. Betting too big can ruin a profitable strategy through variance.
Betting is like poker, where you play differently with different hands. You need to adapt to market changes. Knowing when to hedge or exit is key. You must recognize when your edge is gone and have the discipline to pass, not force action.
Multiple Comparisons Control Bonferroni BH FDR and Guardrails
Every time you test a strategy, you’re playing with fire if you don’t control for multiple comparisons. Betting backtests can be overwhelming with all the numbers. You might think you’ve found the next big thing, but have you really? Or are you just lucky?
Here’s the kicker: if you run a hundred random strategies, you might stumble upon five that seem statistically significant at the p
The Bonferroni correction is strict. It tells you to divide your significance threshold by the number of tests you’re running. Suddenly, that “profitable” strategy looks as convincing as a coin flip. The Benjamini-Hochberg procedure is more lenient, controlling the expected proportion of false positives. Either way, you need guardrails.
Imagine a quant building a betting system with 47 filters. Each filter adds a sliver of “improvement.” The result? A Rube Goldberg machine calibrated to historical noise. Enter the Noise Test: generate 1,000 synthetic price histories by adding random noise to your data, then run your strategy on all of them. If your original backtest sits in the 99th percentile of those noise-adjusted results, congratulations! You’ve likely built a strategy that trades on random squiggles.
Mixing bull and bear regimes into one backtest is like averaging your poker results against both drunk uncles and professional grinders. The blended number? It doesn’t mean a thing. Condition on the regime, control for the multiplicity of your search, and accept that some of your “discoveries” are just statistical ghosts.
| Method | Description | Pros | Cons |
|---|---|---|---|
| Bonferroni Correction | Divides significance threshold by the number of tests | Simple to implement | Very conservative, may miss true positives |
| Benjamini-Hochberg | Controls the expected proportion of false positives | More lenient, balances sensitivity | May allow some false positives |
| Noise Test | Generates synthetic data to test robustness | Helps identify overfitting | Requires computational resources |
Equity Curve Metrics CAGR Max Drawdown MAR and CLV Distributions
In betting, the equity curve is like a Rorschach test. It shows what you want to see, not reality. A 22% CAGR might make you dream of luxury yachts. But a 35% max drawdown might make you think about safer options like Treasury bonds.
The CAGR (Compound Annual Growth Rate) looks great on paper. It shows how fast your money grew. But it’s like a dating profile—it’s too good to be true. The max drawdown shows the real truth. It’s the deepest valley your account faced.
The MAR ratio is a key metric. It’s CAGR divided by max drawdown. A MAR of 0.5 means you risk two dollars of drawdown for every dollar of return. That’s like a trade you wouldn’t make!
CLV (Closing Line Value) is your true north. Beating the closing line shows you have an edge. If not, your backtest might just be luck.
Position sizing is where the magic happens. A strategy with a 1.5 MAR at a 1% Kelly fraction could be great. But at full Kelly, it’s a wild ride most would quit at the worst time.
To understand this better, let’s look at the following table that compares various equity curve metrics:
| Metric | Description | Importance |
|---|---|---|
| CAGR | Annual growth rate of your investment | Indicates overall performance |
| Max Drawdown | Largest drop from peak to trough | Measures risk exposure |
| MAR Ratio | CAGR divided by max drawdown | Efficiency of returns |
| CLV | Difference between your bet and the closing line | Shows skill level |
Understanding these metrics helps you navigate betting strategies with confidence. It’s not just about knowing your average win rate. It’s about seeing the full picture of outcomes and ensuring they hold steady in different markets.
Robustness Tests Season Team Regime and Parameter Sensitivity
Robustness testing is where the real experts shine in betting strategies. It’s not just about winning; it’s about winning consistently. You need to show your strategy can succeed in different situations.
Start with parameter sensitivity. If changing a small detail, like a moving average, ruins your strategy, it’s not solid. A good strategy should stay strong even with small tweaks.
Then, look at seasonality and team-specific regimes. Does your strategy work well at first but then fail? Or does it falter when a key player is out? These are important signs of how long your strategy will last.
Understanding regime awareness is key. Betting strategies need to change with the market. A strategy that works in one situation might not in another. I’ve seen many bettors fail because they didn’t adjust their strategy when the market changed.
The Noise Test is a top way to check if your strategy is solid. It creates fake data to see if your strategy holds up. If your results look too good to be true, they probably are. Many “edges” are just lucky breaks that won’t happen again.
Robustness testing is your chance to prove your strategy is real. It’s a way to make sure your betting backtest is reliable and ready for success.
Attribution Edge from Model vs Timing vs Line Shopping
Ever thought about where your betting edge comes from? Knowing this can make you a pro. It’s not just betting; it’s understanding why you win or lose. Attribution analysis is key here.
Attribution analysis is like an autopsy for your betting wins and losses. Many bettors miss this step. Your betting edge usually comes from three main sources:
- Model Edge: This is your predictive signal, the smart insight that spots mispriced lines. It’s the top prize in betting.
- Timing Edge: Betting early to avoid losing money when the line changes. This edge is real but hard to keep.
- Line Shopping Edge: This means using multiple sportsbooks to find the best odds. It needs no guessing but can make you win.
When you break down your past wins, figure out what part comes from each edge. If most of your edge is from line shopping, maybe your model needs a check. Also, if your edge vanishes with a 30-minute delay, you might be in the timing game, not prediction.
Walk forward analysis is vital here. It lets you test your predictions without timing issues. It’s like poker; knowing if you won from a good hand, position, or table choice matters for future wins.
Improving your edge might not always mean winning more. Sometimes, it’s about making your losses smaller by getting better odds. Remember, transaction costs can also affect your profits.
Reporting Standards Replication Code Seeds and Data Lineage
If your backtest can’t stand up to scrutiny, it’s time to question its very existence. In the realm of quantitative betting, reporting standards are often alarmingly low. With no regulatory body demanding transparency, many bettors are left to their own devices. The result? A landscape littered with unverifiable claims and dubious results.
To truly grasp the essence of a betting strategy, we must first discuss the importance of replication code. This code should be version-controlled, thoroughly commented, and—dare I say—shared with others. If your edge is so fragile that revealing the methodology destroys it, it’s likely just a product of data mining, not a genuine structural inefficiency.
Equally important are the seeds used in your analysis. The random number generator seed for train-test splitting or synthetic data generation must be documented. Without it, your entire analysis is built on a shaky foundation. Change the seed, and your “robust” strategy’s Sharpe ratio could swing by a staggering 40%. That’s not robustness; that’s just a game of chance.
Now, let’s not overlook data lineage. This unsexy but essential aspect forms the backbone of your analysis. Where did your historical odds come from? Were they scraped, purchased, or manually entered? Did they include delisted markets or only the survivors? Were timestamps consistent across sources? I’ve seen betting models built on data riddled with systematic errors—odds that were stale by hours or incorrect grading rules. Such backtests are basically works of fiction.
The multiple hypothesis correction thread ties into this as well. Your reporting should explicitly state how many variations you tested before landing on the final specification. If you tried 200 parameter combinations and only report the best one without adjusting for that search, you’re not conducting an analysis; you’re performing a magic trick.
| Aspect | Importance | Common Issues |
|---|---|---|
| Replication Code | Ensures reproducibility | Lack of version control |
| Random Seeds | Maintains analysis integrity | Undocumented seeds |
| Data Lineage | Establishes trustworthiness | Stale or incorrect data |
| Multiple Hypothesis Correction | Avoids misleading results | Not reporting all variations |
In the poker world, players aren’t judged by their single best session. You shouldn’t judge a betting strategy by its most favorable backtest specification. Let’s strive for rigor and transparency, and perhaps we can turn those campfire stories into solid strategies.
Greenlight Criteria Go Live Thresholds and Stop Rules
Starting live betting is exciting but also risky. It’s like stepping off a cliff. You need to be careful and have a plan to avoid mistakes.
Just because your strategy worked in backtesting doesn’t mean it will work live. You must set clear rules before you start. These rules help you know when to take action.
What are the most important rules? Here are some key ones:
| Criteria | Description | Importance |
|---|---|---|
| Minimum Independent Bets | Avoid correlated observations to ensure results are not just noise. | High |
| Sharpe Ratio | Must clear a hurdle rate based on expected turnover and holding period. | Critical |
| Walk-Forward Stability | Performance should not deteriorate as you approach current data. | Essential |
| Edge Net of Transaction Costs | Gross edge should remain significant after accounting for slippage and execution. | Vital |
Stop rules are like having a guardian for your trading. If things don’t go as expected, stop trading. This is for your own good.
Position sizing is also important. It affects how much you can lose before stopping. This means you need to balance your risk and rules carefully.
The goal is not to avoid losses but to lose in a way that fits your strategy. Knowing when to stop is key.
In short, having clear rules and stop points is vital for live betting. For more on managing your bankroll, see this resource.
Post Deployment Shadow Mode and Performance Reconciliation
Deploying a betting strategy without a shadow mode is like jumping into a pool without checking the water first. It’s risky and could lead to a splash of embarrassment. Shadow mode lets you test your strategy in real-time without risking actual capital. You track hypothetical bets and analyze their outcomes, giving you a clearer picture of your strategy’s performance.
Performance reconciliation is key. This process involves comparing your shadow mode results with your backtest predictions. If your backtest suggested a 4.2% edge, but shadow mode only delivered 1.1%, it’s time to investigate. “The market changed” isn’t a valid excuse without evidence. Discrepancies often stem from execution timing issues, data feed latencies, or the harsh reality that your backtest might have been overfit.
Walk forward analysis doesn’t stop at deployment. It’s an ongoing process. Each month, ask yourself: does the performance distribution align with what you expected? Are the drawdown characteristics consistent with your historical simulations? Adjustments in position sizing should reflect your live edge. If it’s half of what you modeled, your bet sizes should shrink.
Shadow mode is an affordable education in the betting game. Skipping it can lead to costly mistakes. Embrace this phase as a vital part of your strategy’s evolution. After all, knowledge gained from experience is the best teacher.